by Philip Whyte
A broad consensus appears to have emerged across northern Europe on what ails the eurozone. The region's current predicament, on this view, is the result of fecklessness and irresponsibility in geographically peripheral member-states. Countries in the periphery ran into difficulty because they mismanaged their public finances and lost 'competitiveness'. The road to redemption, on this analysis, is for the peripheral countries to consolidate their public finances and embrace supply-side reforms. The task at EU level is to keep member-states on the straight and narrow by making sure that they comply with the fiscal rules and do what is required to remain 'competitive'. This view, which is having a decisive influence on reforms to the way the eurozone is run, coincides with that of the German government. Let us, then, call it the 'Berlin consensus'.
As an analysis of what ails numerous economies across Europe, the Berlin consensus has much to commend it. There is no question that some countries have mismanaged their public finances. Greece, where governments disguised their profligacy by cooking the data, is the most egregious example. Nor is there any question that many 'peripherals', particularly across Southern Europe, face daunting supply-side challenges: low productivity, high drop-out rates from secondary education, inflexible labour markets, insufficient competition in services markets, rapidly ageing populations and low effective ages of retirement are a toxic brew. All these countries are on unsustainable paths and must push through thoroughgoing economic reforms. Depressingly, their reform efforts have been among the most pedestrian in the EU.
So far, so uncontroversial. Is it right, however, to say that the eurozone would have averted crisis if countries had complied with the Stability and Growth Pact and taken the Lisbon agenda of economic reforms more seriously? Nothing is less certain. France and Germany, which violated the Stability and Growth Pact in 2004, do not face funding difficulties in the government bond markets; Ireland and Spain, which complied with the rules until the crisis broke, do. Nor is it clear that macroeconomic imbalances can be pinned on divergences in national 'competitiveness'. Ireland, a flexible economy that scores highly on many indicators of 'competitiveness', is arguably the most troubled (because the most indebted) country in the eurozone. Italy, which scores worse than Ireland on most indicators of competitiveness, is far less indebted.
The problem with the Berlin consensus is that it does not pay enough attention to the demand-side factors that gave rise to the crisis. The cause of the eurozone's macroeconomic imbalances lay on the demand side. In essence, the problem was that demand grew broadly in line with output at eurozone level, but failed to do so at national level. While demand grew faster than output in the periphery, the reverse was the case in the 'core'. Profligacy in the periphery was funded by thrift in the core. This arrangement suited both sides – for a while. Countries in the periphery enjoyed debt-fuelled booms, while countries like Germany could rely on exports to keep growing (in the face of weak demand at home). Export-led growth in the core and rising indebtedness in the periphery were linked: they were reverse sides of the same coin.
Given the amount of capital that was flooding into the deficit countries, there was always a risk that some of it would be wasted on unproductive investments. And so it was. In Greece, the main agent of waste was the government. But the antics of the government in Greece pale in comparison with those of the private sector elsewhere. In Spain and Ireland, the private sector misallocated capital on a truly epic scale. The agents were over-leveraged banks, in both peripheral and core countries, that funded increasingly speculative investments in the property sector. When the property bubble burst and banks' assets turned sour, the direct and indirect costs blew a hole in the public finance. Ireland's deficits and debt exploded because the government guaranteed the liabilities of highly leveraged banks that were too big for the state to save.
At root, the eurozone crisis boils down to an argument about money. Who should pick up the bill for all the capital that was misallocated in the peripheral countries: feckless borrowers, or reckless lenders? Creditor countries, who are currently in the political driving seat, believe the bill should fall on taxpayers in the deficit countries. But it is not clear that this demand is viable – either economically or politically. Some countries in the periphery are probably insolvent, and the medicine they are currently being prescribed risks pushing them into an ever deeper debt trap. It is hard to see how governments in the periphery can indefinitely push through structural reforms if their economies are contracting and their debt burdens are rising. In the end, therefore, some element of forbearance in the creditor countries appears to be inevitable.
What bearing does all this have for the reform of eurozone governance? First, fiscal consolidation and structural reforms in the periphery may be desirable objectives, but they will not restore the most indebted countries to solvency. Second, extending loans on less than generous terms, as Ireland's partners are doing, will buy time but is unlikely to stave off the inevitable: a default on, or restructuring of, peripheral government debt. Third, it is wrong to portray the eurozone crisis as a problem in the periphery alone. The sovereign debt crisis and the banking crisis are inextricably inter-twined. In the peripheral countries, the link is overt. In the core countries it is suppressed. German banks, for example, are under-capitalised and highly exposed to default in the periphery – a fact that the German government is not keen to discuss.
Since a sovereign debt restructuring in the periphery would have repercussions for the solvency of banks in the core, the eurozone needs a crisis management framework to deal with both eventualities. The eurozone needs to establish a framework for orderly sovereign debt restructuring, which would ensure that private-sector creditors share in the pain. And since sovereign debt restructuring would push some European banks into insolvency, the EU needs to develop plans for dealing with this prospect. Solvent sovereigns in the core, such as Germany, will have to decide whether they want to recapitalise their weaker banks, or allow them to survive in their current vegetative state. And countries across the EU must implement resolution regimes that would allow them to wind up insolvent banks in as orderly a fashion as possible.
Philip Whyte is a senior research fellow at the Centre for European Reform
Friday, February 11, 2011


Friday, January 28, 2011
Ireland’s election and the EU: From poster child to enfant terrible?
by Hugo Brady
Ireland will elect a new government on February 25th to replace a discredited administration loathed by most Irish voters. At first sight, it seems unlikely the election will re-open the fundamentals of a bail-out agreed with fellow eurozone members and the IMF last November. The last act of Fianna Fáil, the main party in government since 1997, was to translate the terms of that deal into an initial set of tax hikes and further public spending cuts before leaving office. Nonetheless, the poll – Ireland’s most important for decades – marks a shift in hostility towards the bail-out and the EU in general which its partners would be foolish to ignore.
European benefactors might express shock that Irish attitudes towards the EU have worsened in the wake of the bail-out. To many EU leaders – including José Manuel Barroso, president of the European Commission – they are helping to rescue a country where politicians and regulators, through incompetence or worse, allowed bankers and developers to drive the economy to ruin using other people's money.* That view is correct but cloistered. It takes no account of the part played by the introduction of the euro itself – at a low interest rate hitherto unknown in Ireland – in inflating a runaway property boom. And Ireland's eurozone partners (along with Britain) do expect their money back at a profit, having – they hope – secured the common currency and the unwise investments of their own banks in the process.
Furthermore, the Irish version of events differs sharply from that of its partners, even when adjusted for the natural reluctance of any country to blame itself for its own woes. Most Irish people feel that the rest of the eurozone and European Central Bank imposed a bail-out that their country did not need (Ireland could have limped on until mid-2011 despite its astronomical debts) at an interest rate that it could not afford (5.8 per cent) in an ultimately futile attempt to contain a wider crisis. With a decade of austerity ahead and with no option to default, Ireland's voters gape in disbelief at new demands by continental politicians that it must now raise its low corporation tax rate. By the end of the year, Ireland will have lost 300,000 jobs from a labour market of 2.1 million. The country needs to retain foreign investment as a matter of economic survival.
Perhaps popular disenchantment was always unavoidable, but attitudes amongst Ireland's traditionally pro-EU elites have hardened too. Michael Noonan, the finance spokesperson of Fine Gael – an unambiguously pro-European Christian Democratic party and the one likely to form the bulk of the next government – has characterised the bail-out agreement as being forced on a punch-drunk government by lordly EU and IMF negotiators. Eamon Gilmore, the Irish Labour leader, whose party is likely to secure the finance portfolio in a new coalition, has also demanded a renegotiation of the terms of the agreement, saying the bail-out “clearly won't work. It provides no scope for the Irish economy to grow.”** Even Fianna Fáil – now under a far more effective leader in Micheál Martin, the former foreign affairs minster – will repudiate the agreement in time. And independent commentators in the media and respected think-tanks such as the Economic and Social Research Institute wonder aloud how Ireland will remain a euro country while extricating itself from its current situation.
Irish politics manages to fuse an Italian-style localism, ebullience and idiosyncrasy with the British parliamentary model. Ireland's politicians are usually uninterested in ideology, intensely sensitive to local concerns and poor at strategic thinking, one reason why they were unable to think past the boom. But popular Irish attitudes to national sovereignty closely mirror those of its nearest neighbour. In Britain, euroscepticism became a truly potent political force in the wake of the UK's forced exit from the European Exchange Rate Mechanism in 1992. Since then, pro-Europeans in Britain have dwindled to a small group of progressives. There is every reason to believe that the new generation of Irish politicians entering the scene at this election will view Ireland's difficulties with the euro as the ERM crisis for slow-learners. A flotilla of long-serving parliamentarians are bowing out of politics at this election in favour of younger candidates.
All of this matters doubly because – unlike Britain – Ireland has held a referendum on the future of European integration on average every four or five years since 1987. On the two occasions when Ireland has voted twice on the same treaty, Irish politicians were able to justify this by pointing to the fact that EU membership had been overwhelmingly beneficial to the country. Many voters now recall with bitterness how a desperate government assured them in October 2009 that a second vote on the Lisbon treaty would assist an imminent economic recovery. It will no longer be possible to be so categorial about Ireland's relationship with the EU, also bearing in mind that the country will shortly become a net contributor to the European budget. And the current uncertainty over the fate of the euro itself shows that the EU's constitutional future is by no means settled, as many had hoped when Lisbon was finally ratified.
Make no mistake: it is Ireland's politicians, not the EU, that will rightly be in the firing line on February 25th. But although Ireland may never again be able to serve as an unqualified European success story, the collapse of pro-European sentiment there could well come back to haunt the EU in future. In the 1990s, the IMF learned in Latin America that it is often wise to launch a charm offensive when a new government comes into power in a recipient country undergoing harsh economic adjustment. Ireland's eurozone partners and the ECB would be well advised to follow a similar approach by pre-empting the incoming government's demand for a renegotiation with an offer to lower the interest rate for loans needed to sustain the public finances. In time, the sparing of Irish blushes may save those of many others.
Hugo Brady is a senior research fellow at the Centre for European Reform
* http://www.irishtimes.com/newspaper/breaking/2011/0119/breaking52.html
** http://www.irishtimes.com/newspaper/ireland/2011/0106/1224286876810.html
Thursday, January 20, 2011
Can Greece be saved?
by Katinka Barysch
Will Greece have to restructure its debt? Among most West European economists and investors, this now seems to be a foregone conclusion. The Greeks themselves are not so sure. During a recent visit to Athens, none of the economists and politicians I spoke to thought that restructuring was inevitable or desirable. The Papandreou government looks determined. But to avoid default, Greece would need two things: economic growth and more help from its European neighbours.
Since Greece negotiated its €110 billion financial assistance package with the EU and the IMF last year, it has cut its government deficit by an impressive 6 per cent of GDP. The government has slashed public salaries and pensions, raised VAT and other taxes, and clamped down on ubiquitous tax evasion. Half a dozen big strikes and the occasional outbreak of street fighting notwithstanding, the Greeks have so far remained rather stoic in the face of this unprecedented belt tightening. Most realise that change is needed and hardship inevitable.
The other reason why Greeks have so far stayed calm is that the worst is yet to come. While civil servants, truckers and some other groups felt immediate pain, the population at large has not yet suffered unbearably. After 15 years of rising salaries, most Greeks can cope with an initial drop in income. Those who lose their job or business can usually rely on a tightly knit family network for support.
Greece, however, is not even half way through its deficit cutting programme. The total need for adjustment is 13-15 per cent of GDP. Cutting the first 20 or 30 per cent out of any budget is relatively easy – especially in a budget that contains as much flab as the Greek one. The public sector is overstaffed and, in many places, overpaid; pension entitlements are generous; although 60 per cent of the population lives in the capital, Greece has over 1,000 municipal administrations and 52 regional ones (a new law will cut those numbers by two-thirds); the country’s 150 public hospitals are accounting-free zones, which has contributed to spiralling healthcare costs; public enterprise such as the railways are black holes for government subsidies.
Once the most glaring inefficiencies have been removed, however, further reductions will get a lot harder. After the fat is gone, the government will have to cut bone. Papandreou needs to perform this operation at a time when the economy is in deep recession: by the end of this year, GDP will have contracted by as much as 10 per cent; unemployment is heading towards 15 per cent; among younger people, one in three is out of work; thousands of businesses are closing down every month.
Even if the government managed to stay on track with its plans for budget consolidation, public debt would continue to rise inexorably, to over 150 per cent of GDP by the end of this year. Greece will only stand a chance of generating the revenue needed to service such high debt if it returns to economic growth, and quickly.
The bad news is that in order to regain its competitiveness Greece will require an internal ‘devaluation’ – a fall in real wages relative to its trading partners. Such wage compression will dampen consumption and could even lead to damaging deflation. And it would not even address the deeper problem that Greece makes few things that people in other countries want to buy. Growth since the 1990s was led by consumption and fuelled by cheap foreign credit. To move to a more sustainable growth model, the country requires higher value-added industries and massive foreign investment. Neither will materialise without very thorough economic and institutional reforms. “In terms of institutions, infrastructure and corruption, Greece looks a bit like a third world country”, sighs one Greek fund manager based in London.
The somewhat better news is that Greece’s economy is so inefficient that a series of straightforward changes could kick-start an economic expansion. “In many sectors, our economy resembles Soviet central planning”, explains Yannis Stournaras, who runs the IOBE institute for economic and industrial research. “If we remove stifling regulation and bureaucracy, the economy’s dynamism will be unbound.” IOBE has calculated that liberalisation of the most heavily shackled sectors and professions would lift output by 10 per cent over four years, and probably more once dynamic, growth-boosting effects are taken into account.
Having implemented a first bout of budget-cutting policies, the Papandreou government is now setting to work on structural reforms. If things go according to plan, some 70 ‘closed shop’ professions, from lawyers to pharmacists and civil engineers, will lose many of their privileges and protections. Hiring and firing workers will get easier across the board. State enterprises will be restructured, downsized and sold off. Red tape for businesses will be cut. New incentives will boost investment in green energy, high-end tourism and other potential growth industries.
These plans are already creating fierce opposition from the highly organised groups that will be directly affected. The two main political parties, but Pasok in particular, rely on the trade unions and professional bodies for their core support. “Attacking the closed-shop professions means civil war within Pasok”, predicts Loukas Tsoukalis, head of Eliamep, a think-tank in Athens. Already, some Pasok MPs are grumbling that the reforms are now going too far, too fast. More strikes are inevitable.
Curiously, Greeks tend to sympathise with the plight of even the most molly-coddled public sector workers and privileged professionals. Faced with rising opposition within his own party and public restiveness, Papandreou’s resolve may yet falter.
Even if it does not, Papandreou will face the immovable object of his own state administration. Structural reforms will only boost growth if they are implemented swiftly and effectively. The chances of this happening are slim. A law going back to the post-dictatorship days makes the dismissal of civil servants illegal; even sacking public sector workers who do not strictly speaking enjoy civil service status is considered politically impossible. Each administration since the 1980s has added ‘its’ people to an already outsized state apparatus, often in return for votes and political support. The result is a public sector that is not only hopelessly bloated (roughly 800,000 out of a workforce of five million) but one that is infused with a sense of entitlement, rather than public duty.
Until and unless growth resumes, Greece will struggle to cope with its stifling debt burden. Greeks hope that the EU will step in again to tide the country over until the economy recovers. Many hope that Germany will drop its opposition to joint eurozone bonds, which would help to lower the interest rate at which Greece borrows and refinances its debt. Others suggest that the EU could ‘front-load’ regional aid to boost Greek investment over the next couple of years.
If no further EU help is forthcoming, or the debt burden proves unsustainable, Greece may yet be forced to negotiate a rescheduling or restructuring with its creditors. Since Greek politicians are loath to consider the default option publicly, this would come as a shock to many ordinary Greeks. Many might be directly affected if (as seems likely) a public debt restructuring triggers a crisis within the Greek banking sector and social security funds. Most Greeks would consider default as a terminal blow to the country’s standing inside the EU.
Greeks have traditionally been very pro-EU, and not only because the country has been one of the biggest recipients of EU structural funds since the 1980s. All political parties, with the exception of the Communists, are in favour of more European integration. Remarkably few Greeks have so far blamed the EU (or the IMF for that matter) for the hardship they are going through – although Germans, and Chancellor Merkel in particular, are deeply unpopular for dithering over the bail-out and lecturing the Greeks about their allegedly lazy and lavish ways.
If Greece was forced to restructure, politicians and public opinion could quickly turn against the EU. “The Greeks would say: We’ve been through pain and austerity, and now you drop us”, predicts Panagiotis Ioakeimidis, professor at Athens university and an EU specialist. Some Greeks fear that after default, Greece’s membership in the euro, and the EU itself, may be questioned. That is why the Greeks will hold out fiercely against any pressure to consider restructuring.
Katinka Barysch is deputy director of the Centre for European Reform
Monday, January 17, 2011
Euro crisis: In defence of investors
by Simon Tilford
The eurozone’s fiscal position is better than the US and UK, and the crisis-hit members of the currency union are doing more to strengthen their public finances than either of these countries. So why are borrowing costs so much higher for countries in the eurozone periphery than for Britain and America? Portugal and Greece have lower public deficits than the US, so why do investors fear for their solvency, but not that of the US?
These questions are being put with increasing frustration by eurozone economists, from both the public and private sectors, as well as by policy-makers such as Juergen Stark at the European Central Bank. The inference is that investors are judging countries by different standards. Why else would investors continue to lend to the likes of the ‘profligate’ US and UK, but punish countries whose fundamentals are sounder? Such irrational behaviour by investors, it is argued, is unfairly derailing the hard work being done by governments in the eurozone. Are such frustrations justified?
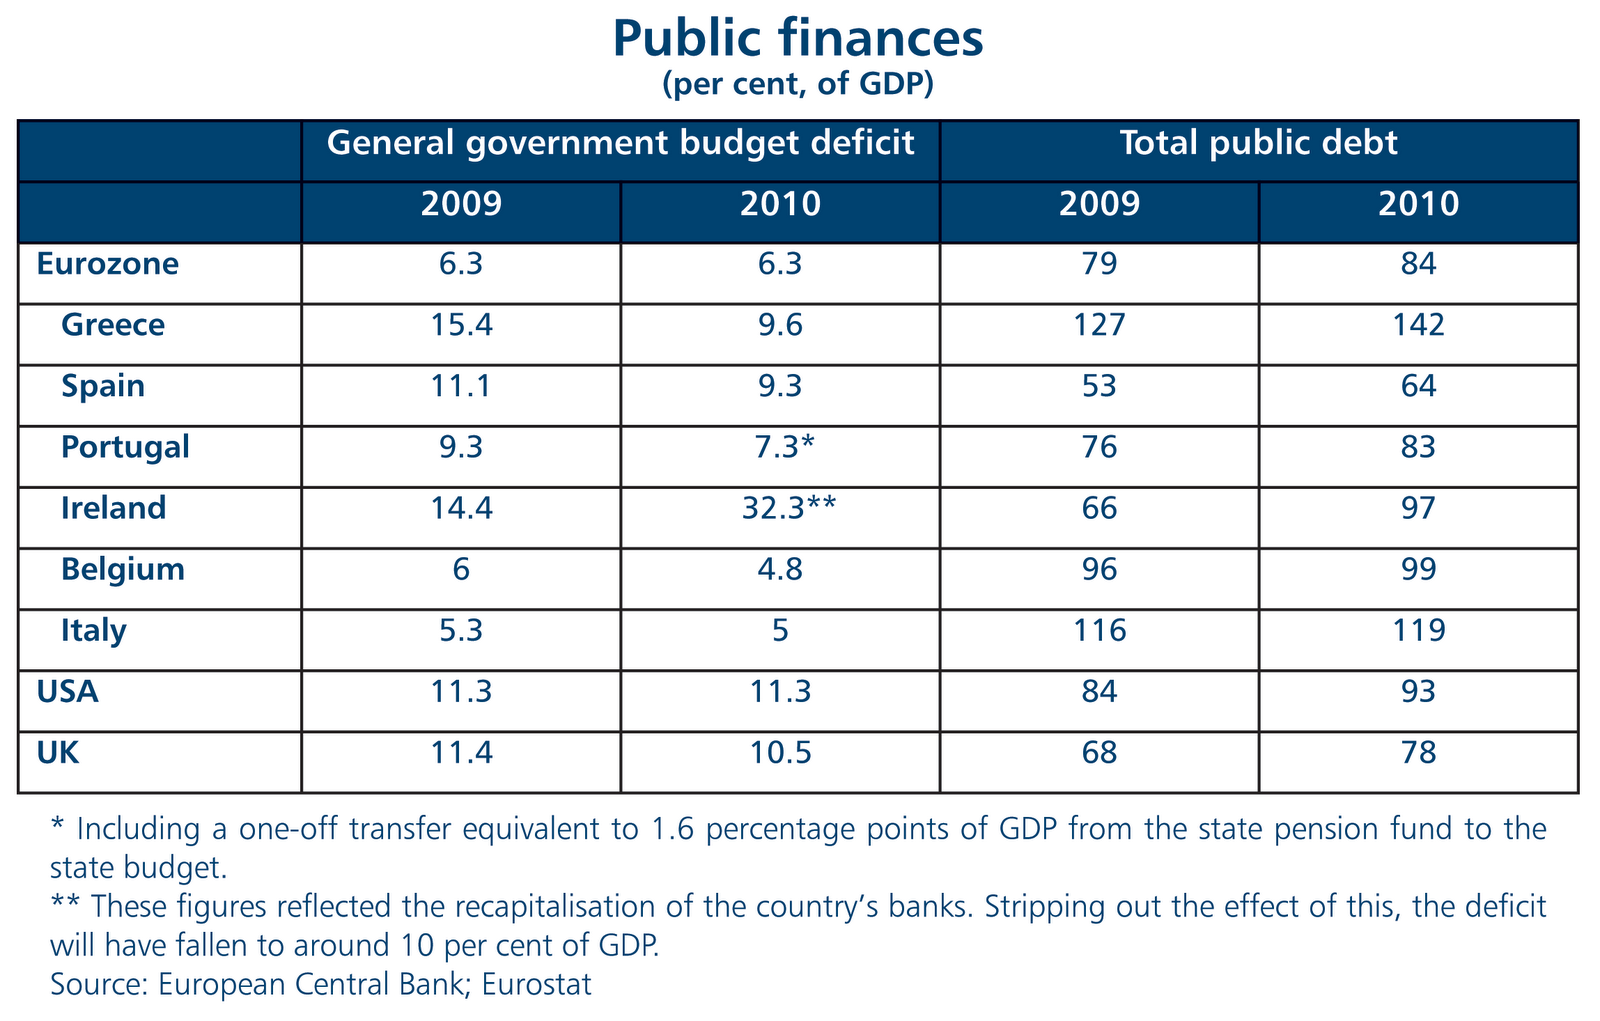
Investors do appear, superficially at least, to be harsh in their attitude towards the eurozone. As Table 1 below shows, the eurozone's aggregate budget deficit is lower than in the UK or the US; its aggregate debt is marginally higher than in the UK, but lower than in the US; and in struggling Spain, public debt is lower than in both the US and the UK.

But anything more than a very superficial analysis shows why investors are right to be concerned about the eurozone. First, there is no federal eurozone budget, so the aggregate budget deficit is only of so much interest to investors. Second, it is countries’ ability to service their debts going forward that determines the risk premium demanded by investors, and to a large extent this depends on their economic growth prospects. While the crisis-hit eurozone economies have made more progress in reducing their borrowing than did either the UK or US, this has been at the cost of economic stagnation. Third, sovereign investors are not just concerned about public debt, but levels of private indebtedness too. They fear that if economic growth remains very weak, governments will end up being liable for some of the private debt.
Eurozone economic growth was a respectable enough 1.7 per cent in 2010 (see Table 2). This was well below the US, but about the same as the UK. However, the eurozone figures masked huge differences. Germany, which accounts for a third of the currency union’s GDP, expanded by 3.6 per cent, whereas Greece’s economy contracted steeply and a number of others barely grew. Stripping out Germany, eurozone economic growth was actually just 1 per cent in 2010. Indeed, the eurozone is still a long way from returning to its pre-crisis level of economic activity: in the third quarter of 2010 eurozone GDP was still 3.2 per cent lower than in the first quarter of 2008. This was better than the UK but far worse than the US, whose economy was almost 2 per cent larger in the third quarter of 2010 than at the outset of the downturn. Not only is real GDP in some of the struggling economies still way below their pre-crisis peaks, but there is little chance of them returning to pre-crisis levels any time soon.

Are investors right to be so pessimistic about the economic growth prospects of the struggling member-states? Yes, because their prospects of economic recovery rest on a strong rise in exports, but the principal way of bringing this about – real devaluation within the eurozone – threatens economic stagnation and rising debt burdens. Because of their membership of the currency union they cannot devalue their currencies, so must reduce their wages and prices relative to their eurozone counterparts. The problem is that this will depress income and lead to deflationary pressures. This, in turn, will make it hard to bring down deficits on a sustained basis (irrespective of how wrenching fiscal austerity is), and will inflate debt servicing costs. A strategy of deflating back to competitiveness might be do-able for an economy with little or no debt, but for the crisis-hit eurozone economies it is high-risk.
Portugal has combined public and private debt of around 320 per cent of GDP. The Portuguese central bank expects real GDP to contract by 1.3 per cent in 2011, while inflation is unlikely to be much more than 1.5 per cent. This implies stagnant nominal GDP (growth in real GDP and inflation). There was much fanfare this week when Portugal successfully sold a modest quantity of government bonds at a yield of 6.7 per cent, but this is a ruinous rate of interest for an economy with Portugal’s prospects. The picture is somewhat better in Spain (hence investors are demanding less of a premium to lend to the Spanish government). Ireland has managed to execute a major internal devaluation within the eurozone, but at the cost of an unprecedented decline in its nominal GDP and an explosion in the country’s debt burden. With Greece’s stock of public debt at 140 per cent of GDP and its economy contracting rapidly, it is hardly surprising that investors have little appetite for Greek bonds.
But what of the structural reforms being pushed through by these countries? Why are investors not taking more account of these? There is no doubt that Spain, Greece and Portugal are now introducing long overdue reforms of their labour markets. These reforms are obviously welcome, and in the long-term should help to boost productivity growth. But a little perspective is needed. Notwithstanding modest moves to free up the markets for professional services in Greece and Portugal, there is little sign of an aggressive drive to open-up these countries’ domestic sectors to more competition. And without such aggressive liberalisation, productivity growth will remain anaemic. Moreover, there are legitimate doubts over the ability of governments to push through an ongoing programme of unpopular reforms when their economies are caught in a cycle of weak economic growth and rising debt burdens. There needs to be light at the end of the tunnel.
What of debt dynamics in the UK and US? Are they not even worse? Both face daunting fiscal challenges and high levels of household indebtedness. And the US at least relies on foreign investors to finance a significant chunk of its budget deficit. But there are several good reasons for investors to be more relaxed about the solvency of the US (and to a somewhat lesser degree, the UK) than the crisis-hit members of the currency union. Unlike their eurozone counterparts, who must rely on deflation to rebalance their economies, the US and UK can rely on currency depreciation to facilitate the necessary adjustment and boost exports. Currency depreciation and very activist central banks in these two countries also ensures that deflation is unlikely to be problem. In addition, both countries have far more flexible product and labour markets than the southern European countries.
In short, the reason why the US and UK can borrow at much lower rates of interest than the similarly indebted members of the eurozone is that the obstacles to economic growth are lower in Britain and America and threat of deflation and mounting social tensions much less acute. Of course, investors could yet take fright if economic recovery in the two countries peters out and their fiscal deficits remain too high. The UK, more than the US, could certainly find itself in this position. But in such a situation, sterling would fall, encouraged no doubt by a further bout of so-called quantitative easing by the Bank of England. And fortunately for the British government, it largely relies on domestic institutional investors to fund its fiscal deficit; this is not so in the case of the currency union’s strugglers.
Unsustainable macroeconomic policies explain investors’ flight from the sovereign debt of the crisis-hit eurozone economies. Until the eurozone demonstrates how the currency union’s peripheral economies are going to avoid stagnation and debt traps, it will be rational for investors to give their sovereign debt a wide berth.
Simon Tilford is chief economist at the Centre for European Reform.
The eurozone’s fiscal position is better than the US and UK, and the crisis-hit members of the currency union are doing more to strengthen their public finances than either of these countries. So why are borrowing costs so much higher for countries in the eurozone periphery than for Britain and America? Portugal and Greece have lower public deficits than the US, so why do investors fear for their solvency, but not that of the US?
These questions are being put with increasing frustration by eurozone economists, from both the public and private sectors, as well as by policy-makers such as Juergen Stark at the European Central Bank. The inference is that investors are judging countries by different standards. Why else would investors continue to lend to the likes of the ‘profligate’ US and UK, but punish countries whose fundamentals are sounder? Such irrational behaviour by investors, it is argued, is unfairly derailing the hard work being done by governments in the eurozone. Are such frustrations justified?
Investors do appear, superficially at least, to be harsh in their attitude towards the eurozone. As Table 1 below shows, the eurozone's aggregate budget deficit is lower than in the UK or the US; its aggregate debt is marginally higher than in the UK, but lower than in the US; and in struggling Spain, public debt is lower than in both the US and the UK.
But anything more than a very superficial analysis shows why investors are right to be concerned about the eurozone. First, there is no federal eurozone budget, so the aggregate budget deficit is only of so much interest to investors. Second, it is countries’ ability to service their debts going forward that determines the risk premium demanded by investors, and to a large extent this depends on their economic growth prospects. While the crisis-hit eurozone economies have made more progress in reducing their borrowing than did either the UK or US, this has been at the cost of economic stagnation. Third, sovereign investors are not just concerned about public debt, but levels of private indebtedness too. They fear that if economic growth remains very weak, governments will end up being liable for some of the private debt.
Eurozone economic growth was a respectable enough 1.7 per cent in 2010 (see Table 2). This was well below the US, but about the same as the UK. However, the eurozone figures masked huge differences. Germany, which accounts for a third of the currency union’s GDP, expanded by 3.6 per cent, whereas Greece’s economy contracted steeply and a number of others barely grew. Stripping out Germany, eurozone economic growth was actually just 1 per cent in 2010. Indeed, the eurozone is still a long way from returning to its pre-crisis level of economic activity: in the third quarter of 2010 eurozone GDP was still 3.2 per cent lower than in the first quarter of 2008. This was better than the UK but far worse than the US, whose economy was almost 2 per cent larger in the third quarter of 2010 than at the outset of the downturn. Not only is real GDP in some of the struggling economies still way below their pre-crisis peaks, but there is little chance of them returning to pre-crisis levels any time soon.

Are investors right to be so pessimistic about the economic growth prospects of the struggling member-states? Yes, because their prospects of economic recovery rest on a strong rise in exports, but the principal way of bringing this about – real devaluation within the eurozone – threatens economic stagnation and rising debt burdens. Because of their membership of the currency union they cannot devalue their currencies, so must reduce their wages and prices relative to their eurozone counterparts. The problem is that this will depress income and lead to deflationary pressures. This, in turn, will make it hard to bring down deficits on a sustained basis (irrespective of how wrenching fiscal austerity is), and will inflate debt servicing costs. A strategy of deflating back to competitiveness might be do-able for an economy with little or no debt, but for the crisis-hit eurozone economies it is high-risk.
Portugal has combined public and private debt of around 320 per cent of GDP. The Portuguese central bank expects real GDP to contract by 1.3 per cent in 2011, while inflation is unlikely to be much more than 1.5 per cent. This implies stagnant nominal GDP (growth in real GDP and inflation). There was much fanfare this week when Portugal successfully sold a modest quantity of government bonds at a yield of 6.7 per cent, but this is a ruinous rate of interest for an economy with Portugal’s prospects. The picture is somewhat better in Spain (hence investors are demanding less of a premium to lend to the Spanish government). Ireland has managed to execute a major internal devaluation within the eurozone, but at the cost of an unprecedented decline in its nominal GDP and an explosion in the country’s debt burden. With Greece’s stock of public debt at 140 per cent of GDP and its economy contracting rapidly, it is hardly surprising that investors have little appetite for Greek bonds.
But what of the structural reforms being pushed through by these countries? Why are investors not taking more account of these? There is no doubt that Spain, Greece and Portugal are now introducing long overdue reforms of their labour markets. These reforms are obviously welcome, and in the long-term should help to boost productivity growth. But a little perspective is needed. Notwithstanding modest moves to free up the markets for professional services in Greece and Portugal, there is little sign of an aggressive drive to open-up these countries’ domestic sectors to more competition. And without such aggressive liberalisation, productivity growth will remain anaemic. Moreover, there are legitimate doubts over the ability of governments to push through an ongoing programme of unpopular reforms when their economies are caught in a cycle of weak economic growth and rising debt burdens. There needs to be light at the end of the tunnel.
What of debt dynamics in the UK and US? Are they not even worse? Both face daunting fiscal challenges and high levels of household indebtedness. And the US at least relies on foreign investors to finance a significant chunk of its budget deficit. But there are several good reasons for investors to be more relaxed about the solvency of the US (and to a somewhat lesser degree, the UK) than the crisis-hit members of the currency union. Unlike their eurozone counterparts, who must rely on deflation to rebalance their economies, the US and UK can rely on currency depreciation to facilitate the necessary adjustment and boost exports. Currency depreciation and very activist central banks in these two countries also ensures that deflation is unlikely to be problem. In addition, both countries have far more flexible product and labour markets than the southern European countries.
In short, the reason why the US and UK can borrow at much lower rates of interest than the similarly indebted members of the eurozone is that the obstacles to economic growth are lower in Britain and America and threat of deflation and mounting social tensions much less acute. Of course, investors could yet take fright if economic recovery in the two countries peters out and their fiscal deficits remain too high. The UK, more than the US, could certainly find itself in this position. But in such a situation, sterling would fall, encouraged no doubt by a further bout of so-called quantitative easing by the Bank of England. And fortunately for the British government, it largely relies on domestic institutional investors to fund its fiscal deficit; this is not so in the case of the currency union’s strugglers.
Unsustainable macroeconomic policies explain investors’ flight from the sovereign debt of the crisis-hit eurozone economies. Until the eurozone demonstrates how the currency union’s peripheral economies are going to avoid stagnation and debt traps, it will be rational for investors to give their sovereign debt a wide berth.
Simon Tilford is chief economist at the Centre for European Reform.
Thursday, January 13, 2011
Reflections on Tommaso Padoa-Schioppa and the euro
By Charles Grant
At the end of last year, Europe lost Tommaso Padoa-Schioppa, an eminent central banker and economist, and one of the founding fathers of the euro. As EU leaders struggle to cope with the continuing euro crisis, they would do well do ponder some of Padoa-Schioppa’s insights on the economics of monetary union.
Following Greece and Ireland, Portugal may soon require a rescue from its fellow eurozone members. With the benefit of hindsight it is only too evident that the euro has suffered from design flaws, and that European leaders have mismanaged the currency. Too many countries joined the euro before they were ready. Fiscal discipline has been too lax, though new rules will make it harder for governments to over-borrow. Some eurozone governments did far too little to promote structural reform, and have therefore suffered from inflexible economies and poor productivity; in 2010, Greece, Portugal and Spain belatedly implemented some structural reforms. The penal rates of interest at which Greece, Ireland and Portugal have had to borrow have revealed the need for a bail-out mechanism and a procedure for ensuring the relatively orderly restructuring of sovereign debt (both are on their way). The behaviour of many banks – and not only in Ireland and Spain – has shown that the tighter system of pan-European financial regulation now being put together is sorely needed.
The statesmen who designed the euro have been criticised for putting politics ahead of economics: motivated by the desire to promote European unification, they ignored the economics – or assumed that once the project got underway, the necessary rules for economic governance would somehow fall into place. There is truth in that criticism, but many people have forgotten that economics did play a role in the birth of the euro.
In 1987, Padoa-Schioppa wrote a report explaining that the exchange rate mechanism (ERM) – which limited fluctuations among many European currencies – could not survive the removal of exchange controls that was agreed in that year. He wrote: “The complete liberalisation of capital movements is inconsistent with the present combination of exchange rate stability and the considerable national autonomy in the conduct of monetary policy.” He also argued that the end of the ERM and the return of currency instability would endanger the single market.
This report convinced Jacques Delors, the then president of the European Commission, and other leaders, that moving towards economic and monetary union (EMU) was urgent. So in 1988 EU leaders tasked a committee – which had Delors as its chairman and Padoa-Schioppa as its joint rapporteur – with drawing up plans for EMU. Delors and Padoa-Schioppa got most of what they wanted, though the Germans forced them – reluctantly – to accept the principle of binding rules on budget deficits. Most of the Delors committee’s report ended up in the Maastricht treaty in 1991. The ERM would not have survived the currency crises of 1992 and 1993 – when the capital markets nearly tore it apart – without the momentum towards monetary union.
In 2000, when a member of the executive board of the European Central Bank (ECB), Padoa-Schioppa wrote a brilliant essay for the CER, ‘Europe’s new economic policy constitution’. He complained about the weakness of the arrangements for co-ordinating national fiscal policies, arguing that if the eurozone could develop its own fiscal stance, the ECB could better manage monetary policy and more easily keep down interest rates. He also warned that the eurozone would not work well unless governments made labour markets more flexible; doing so would facilitate “higher non-inflationary growth. This in turn would increase fiscal sustainability on both the income and expenditure sides of the budget.”
Padoa-Schioppa’s death has deprived Europe of a courteous public servant who was utterly committed to European unity. Many of his insights have long-lasting relevance, and not only on labour markets. The EU’s new procedure for a ‘European semester’, involving peer review of national budgets, is a step towards the fiscal co-ordination he called for. Above all, Padoa-Schioppa understood the relevance of the euro to the single market. If the euro disappeared, giving way to competitive devaluations and wild currency swings, there is a serious risk that member-states would either impose tariffs against each other or resort to hidden forms of protectionism. Alternatives to the euro would not look pretty.
Like Padoa-Schioppa, the CER has long argued that a healthy eurozone requires much more thorough economic reform. In the flurry of regulatory and institutional reforms now underway, one of the most serious underlying problems in the eurozone is not being addressed. This is the growing gap in competitiveness between the eurozone’s core in northern Europe, and the southern states. This has led to large current account imbalances within the eurozone, and these have left the southern countries struggling to grow and to pay back debts.
One economist who foresaw that these imbalances would be a problem was the CER’s Simon Tilford, whose remarkably prescient CER report, ‘Will the eurozone crack?’, was published in September 2006. Simon wrote: “The core problem is that membership seems to have reduced pressure on governments to undertake the reforms needed to ensure the currency union is a success. Freed from the risk of a currency crisis and higher debt service costs, Italy [and the other southern countries have] done little to strengthen public finances, make labour markets more flexible or introduce more competition. The result has been declining productivity, inflation above the eurozone average and a sharp decline in competitiveness relative to other members of the eurozone. Unable to devalue its currency, Italy now risks getting caught in a vicious circle of very slow economic growth and rising debt.”
Simon predicted, rightly, that the markets’ inability to distinguish between the debts of different eurozone countries would lead to a damaging lack of fiscal discipline. He also pointed out that Germany’s “de facto competitive devaluation”, through low wage growth, would exacerbate eurozone imbalances. “While this has massively boosted the country’s competitiveness and its exports, it has depressed consumption and investment, causing the country’s trade and current account surpluses to balloon. An economy as big as Germany’s cannot depend indefinitely on exports to drive real GDP growth, without imposing intolerable pressures on other members of EMU.” On the other hand, “a German economy growing under its own steam would boost demand across the eurozone, cushioning the impact of structural reforms, and crucially, make it easier for other member-states to restore their competitiveness without forcing their economies into a prolonged recession.”
One reason to be gloomy about the euro is the intellectual rift that divides European leaders. It is as though the doctors examining the patient do not agree on the diagnosis or the medicine required. At the risk of some generalisation, leaders from Germanic and Nordic cultures believe that stricter fiscal discipline and structural reform will suffice to cure the patient. Those from Latin and Anglo-Saxon cultures think that medicine is necessary but not sufficient: they also focus on the imbalances and the need for the core countries with external surpluses to generate demand in the eurozone.
Despite all the problems, I expect the euro to survive, because the political will of EU leaders – including those in Germany – to do what it takes to preserve the currency remains strong. But political will on its own will not suffice; Europe’s leaders must also listen to economists if they want to put the euro on a truly sustainable footing.
Charles Grant is director of the Centre for European Reform
Friday, December 17, 2010
Has Ukraine lost appetite for reforms?
In a study on Ukraine published in October, the CER gave President Viktor Yanukovich credit for passing difficult economic reforms but criticised his efforts to suppress political opposition. Since then, reforms have stalled while the concentration of power in the president's hands has continued unabated.
A recent visit to Kyiv has left me deeply worried. The government continues to amass power. This is in part due to the weakness of the opposition – former leaders of the Orange revolution such as former president Viktor Yushchenko and former prime minister Yulia Tymoshenko are genuinely unpopular with voters, who blame them for disappointing economic performance and failure to move Ukraine closer to the EU. Even so, President Yanukovich seems intent on preventing free and fair elections. The October 31st regional poll was marred by widespread use of government powers to help the ruling Party of Regions. The European Parliament notes in its November 25th resolution that "some parties, such as [Yulia Tymoshenko's] Batkivshchyna, were unable to register their candidates". Phil Gordon, the US assistant secretary of state, said that the United States: "does not believe that those elections met the standards of openness and fairness that applied to the presidential election earlier in the year."
The story is not much better on the economic front. Even in those areas, where progress had been made, the government has started to backpedal. For example, the new public procurement law, which the EU helped to draft earlier this year, is being riddled by exceptions: the country's parliament has exempted work on sites for the 2012 European football championship. The EU has viewed the law as key to countering corruption, and its partial reversal dismayed EU ambassadors in Kyiv. Economists also say that the government cheated to comply with a key requirement from the International Monetary Fund (IMF): in order to cut tax refund arrears it simply stopped accepting claims. The IMF is due to decide this month on whether to disburse further aid to Ukraine.
There has been little progress on reforming the country's all-important gas sector. The government has increased domestic gas prices, which has helped to improve the finances of Naftogaz, the country's monopoly – and perennially insolvent – importer and distributor of gas. But there has been no progress on making the company more efficient and transparent. In September 2010 Ukraine acceded to the EU's 'energy community', which groups countries that pledge to uphold each other's security of supply, on the condition that the government separates Naftogaz's gas transit pipelines from other businesses. The Ukrainian parliament passed legislation in July that had ordered Naftogaz to do just that. But nothing has changed: Naftogaz remains untouched and important secondary legislation – to create an independent regulator, for example – is not even under consideration. Meanwhile, Naftogaz is descending into deeper financial trouble. A court in Ukraine has ordered the company to repay nearly $4 billion to one of Ukraine's most powerful businessmen, Dmytro Firtash, who had sued for damages incurred when the previous government cancelled the services of his company in brokering gas purchases from Russia. It is not obvious that Naftogaz has enough money or gas to reimburse Firtash.
The government recently passed a law that would make it easier to explore oil reserves in the Black Sea. These could in the long run lessen Ukraine's dependence on energy imports from Russia. But to extract the reserves, Ukraine needs foreign expertise. So it is baffling that the government has recently imposed a new 40 per cent duty on imports of refined oil (punishing Shell, a key importer) and increased royalties on gas and oil extracted in Ukraine. Foreign energy majors will have little reason to invest in the country. One representative of a Western energy major says that "there is plenty of gas here, in shale and under sea, but no one will tap it because there is zero confidence among investors that they would ever see their money back." Non-energy companies are treated similarly. Deutsche Telekom and Norway's Telenor wanted to buy Ukraine's national telecommunications operator, Ukrtelecom, but the Kyiv government excluded them from the privatisation on a technicality.
Curiously, while the economic reforms have stuttered, relations with the EU have improved, though from a low point. At an EU-Ukraine summit in November, the parties agreed a 'road map' which may eventually allow the Ukrainians to travel to the EU without visas. Talks on a new 'deep and comprehensive free trade agreement' (DCFTA) have also been resumed, after months of paralysis. When the European Commission had threatened in October to cut off talks altogether, President Yanukovich ordered Prime Minister Mykola Azarov "to make all necessary concessions" to restart negotiations. But the order itself is symptomatic of what is wrong with the relationship: Kyiv only pays attention when talks are about to collapse; even then it takes short-term measures: nothing is being done to assess the economic impact of DCFTA on Ukrainian industries or to encourage the losers to move into new lines of business. This guarantees that some of the country's politically powerful oligarchs will eventually revolt against DCFTA.
The EU has limited tools to press for greater political freedoms and proper economic reforms but it is not powerless. The Ukrainians do care what the EU states and institutions think. They have cheered the European Parliament’s November resolution, in which, for the first time, an EU institution (albeit one without decision-making powers in the matter) says that "Ukraine has the right to apply for membership" (something that the Council of Ministers has been reluctant to say). EU High Representative for Foreign Policy Catherine Ashton and senior national diplomats should speak out more forcefully about the state of democracy in Ukraine. EU governments should also use their influence in the IMF to demand real economic reforms. The IMF loans represent the most important leverage that the European governments and the US have in Ukraine today. The current government in Kyiv is capable of tough choices, but only when it feels real pressure.
Tomas Valasek is director of foreign policy and defence at the Centre for European Reform.
Thursday, December 09, 2010
Eurozone: Time for damage limitation
by Simon Tilford
Time is running out to prevent the eurozone crisis from imperilling Europe's banking system and with it the integrity of the currency union. It is beholden on policy-makers to minimise the economic (and hence political costs) to the EU. Three things need to happen: the debts of Greece, Ireland and Portugal need to be restructured as soon as possible; the European Commission and the European Central Bank (ECB) need to do everything to make sure that the adjustments facing the other struggling euro economies are realistic; and there needs to be policy co-ordination between the member-states aimed at ensuring balanced economic growth across the currency union. This requires leadership and an honest and better informed debate about the causes of the crisis. Both are in short supply.
The adjustments facing Greece, Ireland or Portugal were always a tall order. Now that borrowing costs have ballooned, those adjustments are impossible. Under no plausible economic growth forecasts will these economies be able to pay back their debts. However, eurozone policy-makers continue to treat the crisis as one of liquidity rather than solvency, providing indebted member-states with loans (at punitive interest rates) but doing nothing to improve their chances of being able to service them. This is the worst of all possible worlds. Investors have taken fright and pushed up the borrowing costs of countries whose debts might otherwise have proved manageable. Far from limiting creditor losses, they risk spiralling out of control. Piling up more debt when solvency (not liquidity) is the issue is self-defeating.
The bail-out of Ireland simply increases that country's already unsustainable levels of debt, while insulating investors. The ECB and the Commission opposed restructuring the debts of the Irish banking sector. Instead, they have argued for ever more implausible degrees of fiscal austerity in return for extending costly loans. Unsurprisingly, the Irish government's borrowing costs remain prohibitively high. A bail-out of Portugal will be similarly ineffective. It will benefit lucky investors, but do nothing to improve Portugal's prospects. The loss of confidence in the eurozone and resulting surge in borrowing costs threatens to draw Spain into the insolvent camp, ultimately requiring a Spanish debt restructuring. This would be catastrophic for Europe's banks and would impose huge fiscal costs.
Of course, restructuring the debts of Greece, Ireland and Portugal will be costly for creditors. But if debt positions are unsustainable the problem needs to be addressed sooner rather than later. Banks based in eurozone members such as France and Germany, as well as in non-eurozone countries such as the UK and US, would suffer big losses on their investments in the defaulting countries. The ECB would also book losses. This would be messy and governments would have to bite the bullet and recapitalise their banks. But it would ultimately prove less damaging to economies such as Ireland, Greece and Portugal, and the currency union as a whole, than persisting on a course that promises an even bigger restructuring (and bigger losses) down the line.
The second part of the strategy would be to ensure that the adjustment process facing Spain and other hard-hit economies is a manageable one. The ECB could help by launching an aggressive programme of government bond purchases. Monies from the European Financial Stability Fund (EFSF) could also be used to tide the countries over until they regain access to the financial markets on affordable terms. But these countries' fiscal programmes will also have to be consistent with a return to decent economic growth. Crucially, cuts in spending on education and infrastructure must be kept to a minimum, as these would further reduce growth potential. Reforms of pension and healthcare systems would go a long way to address investors' concerns about the long-term sustainability of countries' fiscal positions.
The third part of the strategy – rebalancing economic growth in the eurozone – will be the hardest to execute, but is essential if future crises are to be avoided. Governments need to support the Commission's drive to foster closer economic integration and to co-ordinate their policies to ensure that they are compatible with balanced economic growth across the eurozone. Huge current account balances are not consistent with a stable currency union, because one way or another they require massive (and hence politically and economically destabilising) transfers between the participating economies. However, even if trade imbalances are reduced, there will have to be greater fiscal supra-nationalism. This could take the form of a common E-bond, some minimal fiscal union, or ideally a combination of the two. Without some element of fiscal supra-nationalism, the adjustment costs facing countries that cede trade competitiveness within the eurozone will simply be too high.
However unpalatable these measures are to eurozone governments, the European Commission and the ECB, they can all be done if governments can summon the political will. Governments have to explain to their voters why debt relief for Greece, Ireland and Portugal and the resulting injection of public funds into banks is necessary in order to head off far greater costs down the line. They have to summon the political courage to make the case for greater economic integration. A fiscal union can also be fashioned in such a way that limits moral hazard. But all of this requires leadership, not least from Germany. The fact that the alternative – a series of ever larger and ineffective bail-outs, culminating in far bigger defaults and a systemic banking sector crash – is much worse, ought to focus minds. After all, under that scenario the political glue holding the union together could dissolve altogether.
Simon Tilford is chief economist at the Centre for European Reform.
Monday, November 29, 2010
The 'new' Poland and its neighbours
by Tomas Valasek
Poland is shedding its 'new member-state' image and is instead trying to join the exclusive club of big EU countries. It is a laudable and so far largely successful goal, but not one without risks. To become a big EU player, Poland needs to continue cultivating its role as a regional leader in Central and Eastern Europe.
Poland is riding high. Whereas all other EU economies slumped last year, Poland's grew by 1.7 per cent. Warsaw has patched up relations with Berlin and Moscow, with noticeable results: German Foreign Minister Guido Westerwelle's first foreign trip was to Warsaw, and Russian politicians handled the tragic plane crash that killed the Polish president and other leaders with unusual tact. Poland's dynamic foreign minister, Radek Sikorski, is all over Europe, dispensing advice on how to reform the EU's neighbourhood policy, democratise Belarus, and revamp NATO's nuclear posture. In a single day alone last month, Russia's Foreign Minister Sergey Lavrov, former US Secretary of State Madeleine Albright, US Assistant Secretary of State Phil Gordon, US Assistant Secretary of Defence Alexander Vershbow and a senior US congressional delegation dropped by Warsaw for separate visits.
The 'new' Poland was born in 2007, when the centre-right government of Prime Minister Donald Tusk replaced the controversial Kaczynski government. Tusk's team decided that Poland was to shed its labels of being reflexively Russophobic, anti-German and Atlanticist – which had led to Warsaw at different points vetoing EU-Russia negotiations and seeking to slow common EU defence policy. Instead, the government briefed Russia on Poland's plans for missile defences (which Moscow felt uneasy about), invited Prime Minister Vladimir Putin to the anniversary of the outbreak of Word War II and launched consultations with Germany on the EU's eastern policy. Warsaw also made common EU defence a priority for its EU presidency in 2011.
Poland's revamped foreign policy has been a great success: along with the country's economic resilience, it has catapulted Poland to a position of prominence in Europe without weakening its bond with the US. Relations with Russia are at their highest point since the end of the Cold War. This transformation has inflated the country's confidence: "We are no longer a playground but a player", boasts one government minister. Poland's view of its place in Europe has been transformed, too. The 'old' Poland was a Central European leader. The 'new' Poland sees itself as a European power on a par with France and Germany. Polish diplomats speak fondly and frequently of a 'Weimar Triangle', in which France, Germany and Poland will discuss matters of European security. In many ways it is already working: Germany's and Poland's foreign ministers wrote a joint paper on strengthening the EU's eastern policy and they went to Minsk together to warn the Belarusian governments against falsifying elections. Diplomats say that lower-level co-operation between German and Polish officials is even more intense.
The Polish-Russian 'reset' has been the most notable result of Warsaw's policy reversal. It started for largely tactical reasons – as a way of boosting Poland's standing in Europe. But Russia's positive response has had an interesting psychological effect. When one speaks to Polish diplomats today they leave the impression that they want the relationship with Russia to look successful almost irrespective of what it delivers because the dialogue with Moscow makes Poland feel relevant and strong. Although most Poles are still wary of Russia, Polish politicians and officials appear more prepared than other Europeans to believe that Russia's 'modernisation partnership' with the EU will transform the country. Polish diplomats also sound less suspicious of Russian intentions, for example in meddling in Central Europe, than most of their EU counterparts.
While Poland has received more attention from West European capitals and improved its ties with Moscow, its links with its immediate neighbours have cooled. Relations with Lithuania are the worst they have been in decades. Diplomats from other 'Visegrad Four' states (Hungary, Czech Republic and Slovakia) grumble that it has become difficult to get their Polish colleagues to focus on regional projects such as new interconnections between oil and gas networks in Central Europe. When the Visegrad countries hold a ministerial meeting, Poland usually sends a deputy to meet with other countries' senior ministers.
This is partly Poland's neighbours' fault; they do not always make attractive partners. Some Central European countries are not serious about defence whereas Poland is a military power and one of a few countries to spend close to the NATO-recommended two per cent of GDP on defence (Hungary and Slovakia are already below, or falling below, the one per cent mark). Others, like the Baltic states, have been reckless with their economies and needed to be bailed out by the IMF, whereas Poland is proudly growing. But Warsaw's relations with new EU members have also cooled because Poland is increasingly adopting a 'big country' mentality. Like the UK, France and Germany, it gives smaller countries less attention than it gives the big ones. Above all, the Poles seem intent on shedding the 'new member' label. A commonly-expressed opinion in Poland is that "the new divisions in Europe are not between the East and West but between the [frugal and responsible] North and the [free-spending and reckless] South". In the eyes of other Central Europeans, Poland appears to be deliberately distancing itself from its traditional friends in the neighbourhood.
This is an understandable instinct; all 'rising powers' grapple with how to balance old friendships with new opportunities for partnership with the big states. But Poland's shift to 'big country' mentality is not without risks. Despite all the notable successes, Poland's new status is still fragile. Germany and France will remain preoccupied with saving the euro for the foreseeable future – an endeavour in which Poland as a non-euro member does not have much of a say. Even in areas where Poland thinks it should play a pivotal role now, it is not always taken seriously. Germany and France held a controversial three-way summit with Russia on European security, much to Poland's dismay (one of the main points of repairing relations with France and Germany was to stop them talking to Russia over Polish heads). Poland's charm offensive also comes at a difficult time: the eurozone crisis has made all EU countries more selfish and tetchy. Poland risks being caught in no-man's land: not yet taken fully seriously by Europe's biggest states but no longer seen by the rest of the new EU countries as a natural leader.
Poland should hedge its bets by simultaneously cultivating links to Germany and France while keeping its old friends close. Paris and Berlin take Warsaw seriously partly because Poland is a regional power: the four Visegrad countries have more votes in the EU's Council of Ministers than the Franco-German duo, and many more when the Baltic states are added. Poland, by virtue of its size and prominence, is the region's natural leader. This gives Warsaw real power in the forthcoming debates such as the one about the next EU budget framework starting in 2014. The more effective Poland becomes at corralling Central European votes, the more likely Paris and Berlin are to seek co-operation with Warsaw.
Tomas Valasek is director of foreign policy and defence at the Centre for European Reform.
Monday, November 15, 2010
Eurozone policy-makers are playing with fire
By Simon Tilford
There is an awful inevitability about the latest instalment of the eurozone crisis, which looks highly likely to culminate in Ireland being forced to seek a bailout from the European Financial Stability Fund (EFSF). As soon as German and French leaders raised the spectre of private holders of government bonds incurring losses under a permanent crisis resolution mechanism, borrowing costs for the struggling members of the eurozone were only going to increase. Unless the EU changes track and agrees to make the EFSF permanent and the European Central bank (ECB) steps up its purchases of the hard-hit countries’ government bonds, investors will believe that default is inevitable and demand correspondingly punitive interest rates. Contagion to other member-states will be all but inevitable. If, and when, it reaches Spain, the crisis risks spiralling out of control.
Taken out of context there is obviously merit to the Franco-German proposal. But the timing could not have been more damaging. The defence of the proposal – that existing bonds would not be affected, just those issued after 2013 when the new crisis resolution mechanism would replace the EFSF – is illogical. In 2013, Greece, Ireland, Portugal and whichever other countries are in this group by then will have to pay ruinously high interest rates to borrow money. The EU will then have to choose between launching an open-ended bail-out of the countries in question, or push ahead with a restructuring of their debts. The latter would, of course, leave the current holders of these countries’ debts nursing losses, and explains why investors have taken fright.
Investors are calculating that voters in the fiscally sound member-states would baulk at an open-ended bail-out. They are right to be sceptical as the number of countries that would be strong enough to participate in such a bail-out is worrying small. For example, it is unlikely that Italy could really participate in a major bail-out without investors looking askance at its own position. Italy is not confronted with the aftermath of a housing market crash, but the country has a very high level of public debt (around 115 per cent of GDP) and extremely poor economic growth prospects. Belgium is in a similar position.
Instead of making a bad situation worse the eurozone should concentrate its efforts on debating how the EFSF will be made permanent, ideally as the embryo of some kind of minimal fiscal union. Without a permanent mechanism to support member-states, it is hard to see how order is to be restored to the bond markets. The current strategy of austerity and debt-deflation on the struggling member-states is bankrupt and self-defeating. If these countries were able to devalue it might work by boosting the trade competitiveness of their goods and pushing up inflation, hence reducing the risk of deflation. Similarly, if there was going to be serious action to address trade imbalances within the currency union, they might have a chance of generating export-led growth. As it stands a number of member-states are effectively insolvent and caught in a vicious cycle. The collapse of economic growth has devastated tax revenues, while deflation is pushing up the real value of their debts.
For its part, the ECB should be loosening monetary policy and stepping up its strategy of bond purchases in an effort to save the currency union. But the next move in eurozone interest rates will be up, and the ECB is committed to winding-down its bond purchases. In light of the risk of contagion to other member-states, including Spain, the ECB’s current strategy is much riskier than the potentially inflationary impact of such bond purchases. With much of the eurozone economy stagnant and German growth being driven largely by exports rather than domestic demand, the threat of a surge in inflation is imaginary.
The initially slow and disjointed response of eurozone policy-makers to the eurozone crisis was forgivable. After all, the currency union comprises 16 sovereign governments and there had been no contingency planning for such a crisis. Deciding what to do was never going to be easy. What is less forgivable is that they continue to underestimate the severity of the crisis and what is at stake if they fail to contain it. Instead of questioning the rationality of the investors, eurozone policy-makers need to pay more attention to what is driving market sentiment. The eurozone’s strategy for dealing with the crisis now points to default across the currency union’s periphery. The markets can hardly be blamed for pricing in such a likelihood.
Simon Tilford is chief economist at the Centre for European Reform
Wednesday, November 03, 2010
Europe dances to Germany's tune
by Charles Grant
For much of this year, the response of European leaders to the eurozone crisis has been hesitant and fractious. But when the European Council met in Brussels on October 28th and 29th, the EU appeared to be acting with greater purpose and sense of direction. One reason for this change is that most member-states – including France – are now willing to swallow large doses of German leadership. Chancellor Angela Merkel's influence was evident on the three key issues discussed by the summit: tightening rules on economic governance, setting up a new institution to deal with countries unable to borrow in the markets, and revising the EU treaties. However, Germany’s leadership has also brought problems. One is that Germany's determination to get its way has bruised several smaller states, as well as the Commission and the European Central Bank. Another is that its reluctance to discuss imbalances within the eurozone has prevented the EU from taking serious action to tackle them – though the imbalances have (in the view of many countries) contributed to the euro crisis.
On the first key issue, the summit adopted the report of the task force led by Herman Van Rompuy, the European Council president, on 'Strengthening economic governance in the EU'. The implementation of the report will mean stricter and more automatic punishments for countries that borrow too much, as the Germans – backed by the Austrians, Dutch, Finns and Swedes – have called for. Sensibly, the report says that the EU should focus not only on governments' budget deficits, but also the overall level of debt. The task force also considered the delicate subject of economic imbalances in the eurozone (the Germans do not like being told that their unwillingness to spend, and their current account surplus, contribute to inadequate demand and current account deficits in southern Europe). The report says it is more urgent to tackle imbalances in countries with big current account deficits than those in the surplus countries, but it does propose monitoring of imbalances and disciplinary procedures for all those who fail to act on recommendations to tackle imbalances.
On the second issue, the new institution, EU leaders agreed to establish a 'crisis resolution framework' to replace or supplement the European Financial Stability Facility (EFSF) that they designed last May to support governments unable to borrow in the markets. Merkel has been unwilling to prolong the three-year life of the EFSF, fearing that Germany's constitutional court could declare it in breach of the Maastricht treaty's no-bail out rule (she also knew that giving the EFSF a finite life would increase her leverage in the arguments on eurozone governance). EU leaders have not yet agreed on how the new body will work, but it will probably be a kind of European Monetary Fund that both lends money (with strict conditions attached) and facilitates an orderly restructuring of the debt of countries that cannot repay what they have borrowed.
The Germans say this restructuring should lead to private sector creditors taking a loss, and many governments go along with that. But at the summit Jean-Claude Trichet, the president of the European Central Bank, and the leaders of some southern states – who worry about their ability to borrow – argued against establishing that kind of restructuring mechanism at this stage. It could deter investors from lending to eurozone governments, Trichet argued, and make it even harder for them to service their debts. The Germans responded that tax-payers should not bear all the cost of bail-outs, and that markets should fret about potential losses in order to discipline borrowers. The markets now seem to be doing that job – perhaps too well. Since the summit the cost of borrowing for the southern Europeans has risen to as high as it was before the EFSF was hatched in May (though the governments concerned started to tighten their belts several months ago). The Germans will face stiff opposition on the issue of creditors taking losses. But since they will be responsible for providing the biggest share of any rescue package, they are likely to win the argument.
On the third issue, treaty change, the summit asked Van Rompuy to report back in December on whether the current treaties need to be amended to establish the crisis resolution mechanism. The answer to that question is already clear. For many months the Germans have argued that treaty change was needed to ensure that a new mechanism did not fall foul of their constitutional court. However, most governments – having spent the best part of a decade sorting out the Lisbon treaty – did not want another round of treaty change. Then at the Franco-German summit in Deauville on October 19th, Merkel persuaded France's president, Nicolas Sarkozy, to back treaty change (in return for a modest weakening of some sanction mechanisms). At the European Council most other leaders followed them, if only grudgingly – though Luxembourg's Jean-Claude Juncker and the Commission's José Manuel Barroso argued against treaty change.
The heads of government now seem confident that a small treaty change can be achieved without too much pain. They have reached a tacit understanding to limit the change to the establishment of the new institution, and to rule out any other amendments. The Lisbon treaty contains a 'fast track' procedure that allows the heads of government to agree a change, by unanimity, without the need for a convention (the mix of MPs, MEPs and government representatives that drew up the constitutional treaty that later became the Lisbon treaty) or an inter-governmental conference. But two conditions must be satisfied: the change must not transfer powers to the EU, and it must concern the implementation of EU policies, rather than the fundamentals of the Union. The clause the Germans want should meet those conditions.
The fast-track procedure still requires each member-state to ratify the amendment. The Irish and the Danes seem to think they can avoid referendums. In the Netherlands, the populist Dutch Freedom Party and the left-wing Socialist Party are both threatening to demand a referendum, but they lack a parliamentary majority. In the Czech Republic, President Vaclav Klaus could create problems, as he did by delaying the ratification of the Lisbon treaty. In any case Czech eurosceptics are likely to challenge the amendment in the constitutional court, on the grounds that it gives the EU more power and therefore merits a referendum. Britain will not be affected by the new rules on eurozone governance, since it has an opt-out from treaty provisions on the euro. Nevertheless Conservative eurosceptics want Prime Minister David Cameron to block treaty change until the other member-states grant Britain new opt-outs from the treaties in areas such as social policy. Cameron seems determined to face down the eurosceptics. He will accept the amendment so long as other governments help him constrain the growth of the EU budget. At the moment France, Germany and about half the member-states are backing Britain's efforts to hold the rise in next year’s budget to 2.9 per cent.
The Germans did not get everything they wanted at the summit. There was little support for their scheme to deprive governments that borrow too much of voting rights. They have had to accept the Van Rompuy report's argument that imbalances should be monitored. But the Germans achieved most of their key objectives. France had opposed stricter rules and quasi-automatic penalties for over-borrowed countries, a formal debt restructuring mechanism, and treaty change. But now it has accepted those German priorities – without appearing to get a great deal in return.
Visiting Paris just after the summit, I was struck by the deferential tone of some French officials when they talked of Germany. They noted that Germany is in a supremely self-confident mood because of its export surge to emerging markets. They thought this was not the right time to tell the Germans that their economic model was marred by a low level of domestic demand, and that that was aggravating the eurozone crisis. Much better to suggest gingerly that Germany would benefit from taking specific steps such as increasing investment and spending on R&D, lengthening shopping hours and getting more women into the workforce. Such steps would in the long term help to rebalance the eurozone. These French officials may be right on the tactics of how best to deal with the Germans.
In Paris, some senior figures fret about Germany's seemingly superior economic performance, compared to France and other EU countries, and about its economic structure – very focused on emerging markets – which seems to be diverging from that of its partners. "Will Germany lose interest in the EU?" they ask. For several years the French – and many others – have worried about Germany becoming less 'European' and more focused on the east, for example through its special relationship with Russia.
One French response is to stay close to the Germans in order to retain influence with them. That has been evident in Russia policy: in recent years France has emulated Germany's soft approach towards Moscow (which is not to say that that policy is necessarily wrong). And that response has also been evident on the euro. At the Brussels summit several smaller member-states complained about having to fall in behind deals stitched together by Paris and Berlin. But so long as the French continue to back the Germans on eurozone governance, their partners – and the EU institutions – have little choice but to follow.
Charles Grant is director of the Centre for European Reform
Subscribe to:
Posts (Atom)